Wallet App Development in 2026: Cost, Features & Complete Guide
Explore wallet app development in 2026, including digital wallet features, development costs, payment integrations, and security considerations.
Wallet App Development in 2026: Cost, Features & Complete Guide
Digital wallets are changing how people pay, transfer money, manage transactions, and interact with businesses. From mobile payment applications and prepaid wallets to loyalty platforms and financial super apps, digital wallet technology enables businesses to deliver faster, more convenient digital experiences.
For companies planning a new financial product, wallet app development in 2026 involves much more than building a mobile interface. A successful wallet requires secure authentication, reliable transaction processing, appropriate financial integrations, accurate transaction records, fraud prevention, and a scalable backend architecture.
Businesses in Qatar have additional considerations, including integration with local payment infrastructure, regulatory requirements, customer identification, and support for Qatari riyals.
So, how much does wallet app development cost? Which features should a digital wallet include? How long does development take, and which technologies should businesses choose?
This guide answers these questions and explains how to plan, develop, secure, and launch a digital wallet application.
What Is Wallet App Development?
Wallet app development is the process of designing, building, testing, and maintaining a mobile or web application that enables users to manage digital payment credentials, stored monetary value, loyalty balances, or other supported digital assets.
Depending on its purpose, a wallet may allow users to:
Store supported payment card credentials or payment tokens.
Transfer money between eligible accounts.
Pay merchants through QR codes or other payment methods.
View transaction histories and payment receipts.
Manage prepaid balances or eligible e-money.
Receive refunds and transaction notifications.
Store loyalty cards, coupons, tickets, or membership credentials.
Connect with supported banks, payment providers, and merchant systems.
Not every wallet performs all these functions.
For example, a loyalty wallet may store reward points without handling monetary transactions. A merchant payment wallet may initiate payments through a licensed provider, while a stored-value wallet may involve regulated e-money services.
The product's intended function determines its technical architecture, security requirements, integrations, regulatory responsibilities, and development budget.
Why Are Businesses Investing in Wallet App Development in 2026?
Digital wallets can simplify payments and help businesses create more connected customer experiences. Their value depends on the business model, customer needs, and quality of implementation.
1. More Convenient Digital Payments
Customers increasingly expect to complete transactions through their smartphones.
A wallet can bring supported payment methods, transaction records, and payment confirmations into a single interface.
For example, a retail business could allow customers to select an eligible payment method, confirm a purchase, and receive a digital receipt without repeatedly entering payment information.
The actual payment process depends on the wallet's integration with the relevant payment infrastructure.
2. Faster Money Transfers
Some wallet applications support transfers between eligible users, accounts, or payment providers.
A properly integrated wallet can simplify recipient selection, transaction confirmation, and payment-status tracking.
However, instant transfers should only be promised when the connected payment infrastructure supports them.
3. Improved Customer Engagement
Businesses can combine wallet functionality with loyalty programmes, membership benefits, promotional offers, and personalized notifications.
A retail application, for example, might display reward points earned from previous purchases and allow eligible customers to redeem them during checkout.
This gives customers a practical reason to return to the application.
4. Better Transaction Visibility
Wallet applications can provide searchable transaction histories, payment statuses, receipts, and spending summaries.
These capabilities help users understand their activity and reduce confusion about completed, pending, failed, or reversed transactions.
For business operators, administrative dashboards can provide operational information, subject to applicable privacy and access controls.
5. Integration With Existing Business Systems
Wallets can connect with e-commerce platforms, customer relationship management systems, enterprise resource planning software, merchant payment gateways, and customer support tools.
Businesses planning a broader digital platform can explore custom software development services to understand how application functionality can be connected with existing operational systems.
Types of Digital Wallet Applications
Choosing the correct wallet model is one of the most important decisions in the development process.
Different wallet types have different operational, financial, and technical requirements.
Wallet type | Primary purpose | Typical features | Main consideration |
|---|---|---|---|
Mobile payment wallet | Facilitate supported digital payments | Payment credentials, authentication, receipts | Payment provider and platform compatibility |
Stored-value wallet | Hold eligible prepaid monetary value | Wallet balance, deposits, payments, withdrawals | E-money and payment-service regulations |
Peer-to-peer wallet | Support transfers between users | Recipient selection, transfers, transaction history | Transfer limits, identity verification, fraud controls |
Merchant wallet | Support merchant collections and settlements | QR payments, transaction records, settlement reports | Merchant onboarding and payment integration |
Loyalty wallet | Manage customer rewards | Points, coupons, membership cards | Loyalty rules and business-system integration |
Closed-loop wallet | Facilitate payments within a defined business ecosystem | Internal balance, purchases, refunds | Legal classification and permitted usage |
Multi-currency wallet | Manage supported currencies | Currency balances, conversion information, transfers | Exchange-rate sources, fees, and applicable permissions |
Digital identity or credential wallet | Store supported digital credentials | Membership cards, tickets, eligible identity credentials | Credential standards and privacy |
These categories are not mutually exclusive. A product may combine several functions.
For example, a retail wallet could combine loyalty rewards with payments processed through an external payment provider. A financial wallet could offer balance management, transfers, and merchant payments.
Important: A wallet that displays payment information is not necessarily authorized to hold customer funds or independently execute financial transactions. The legal and operational model must be established before development begins.
Essential Features of a Wallet App
The best feature set depends on the intended users and the services the application is authorized to provide.
For a minimum viable product (MVP), prioritize the functions needed to deliver the core service securely and reliably.
1. User Registration and Login
The registration process should make account creation straightforward while protecting user accounts.
Common capabilities include:
Registration using an approved identifier.
Phone or email verification.
One-time passwords where appropriate.
Secure password creation and recovery.
Multi-factor authentication for suitable risk scenarios.
Device registration and session management.
Account recovery procedures.
If the wallet provides regulated financial services, onboarding may also require identity verification and additional customer information.
Registration requirements should be based on the service's risk profile and applicable regulations rather than convenience alone.
2. Digital Wallet Dashboard
The dashboard gives users an overview of their wallet.
Depending on the product, it may display:
Available or recorded balance.
Recent transactions.
Linked payment methods.
Payment and transfer shortcuts.
Loyalty points.
Pending transactions.
Security notifications.
Account settings.
The interface should distinguish clearly between available funds, pending amounts, promotional credits, and other balances.
This is especially important when different balances have different usage restrictions.
3. Wallet Balance Management
A wallet that holds monetary value needs reliable balance management.
Its backend should track the financial events that affect each account, including eligible deposits, payments, refunds, adjustments, and withdrawals.
A well-designed implementation should support:
Accurate balance calculations.
Transaction references.
Defined transaction states.
Reconciliation with payment-provider records.
Reversal and refund workflows.
Audit trails.
Detection of duplicate transaction requests.
The system should not depend solely on a balance displayed in the mobile application.
For financial wallets, authoritative transaction records and balance calculations should be managed by the trusted backend or authorized financial infrastructure.
4. Money Transfers
A transfer feature may allow eligible users to send funds to another wallet or supported account.
Useful capabilities include recipient identification, transfer limits, confirmation screens, transaction status, and digital receipts.
The system should also handle situations such as insufficient funds, invalid recipients, network interruptions, rejected transfers, and delayed provider responses.
For example, if a user submits a transfer and the network connection fails, the application should check the transaction's actual status before allowing the user to initiate another payment.
This helps prevent duplicate transfers.
5. QR Code Payments
QR code payments can simplify checkout in physical stores and other supported environments.
A wallet might allow users to scan a merchant's QR code, review the merchant details, confirm the amount, and authorize the payment.
The implementation should verify the payment request with the relevant backend or payment provider.
A QR code should not automatically be treated as proof that a payment has succeeded.
The application should display confirmation only after receiving an authoritative transaction status.
6. Payment Method Management
Depending on the business model, users may be able to link supported cards, bank accounts, or external payment services.
Potential functions include:
Adding or removing supported payment methods.
Verifying a payment method.
Viewing masked payment details.
Selecting a default method.
Managing expired or invalid methods.
Token-based payment integration.
Businesses should avoid storing raw card details unless the architecture and compliance arrangements explicitly permit it.
Where possible, use established payment providers and tokenization services to reduce exposure to sensitive payment information.
7. Transaction History and Receipts
Transaction history helps customers understand their financial activity.
Useful functions include:
Date-based filtering.
Transaction categories.
Payment references.
Merchant details.
Amount and currency.
Pending, completed, failed, or reversed status.
Downloadable or shareable receipts where appropriate.
The application should distinguish between an unsuccessful transaction and a transaction that is still awaiting confirmation.
Clear status information reduces unnecessary support requests.
8. Notifications and Alerts
Notifications can inform users about important account activity.
Examples include:
Successful payments.
Incoming transfers.
Failed transactions.
Refund updates.
Login attempts.
Changes to account settings.
Unusual activity alerts.
Sensitive information should not appear unnecessarily in lock-screen notifications.
Users should also be able to manage nonessential notification preferences without disabling important security alerts.
9. Identity Verification and KYC
Know Your Customer (KYC) processes help regulated financial providers verify customer identity and assess relevant risks.
Depending on the service and applicable rules, onboarding may involve identity documents, customer information, identity checks, risk screening, or additional verification.
The application should communicate verification requirements clearly and protect the information collected.
Identity verification is not simply an interface feature. It can involve third-party verification services, manual review workflows, retention policies, and regulatory reporting obligations.
10. Customer Support
Financial applications need a clear way for users to report problems.
Support functionality may include:
Help articles.
Frequently asked questions.
Secure support requests.
Transaction-related queries.
Dispute and complaint submission.
Account recovery guidance.
Escalation for suspected fraud.
Support staff should only have access to the information required to resolve their assigned cases.
11. Admin Dashboard
A secure administrative dashboard allows authorized personnel to manage the wallet's operations.
Depending on the business model, features may include:
Customer account management.
Verification status review.
Transaction monitoring.
Merchant management.
Refund and dispute workflows.
Support case management.
Configurable transaction limits.
Operational reporting.
Audit logs.
Role-based permissions.
Administrative access should be protected by strong authentication and appropriate approval procedures.
High-risk actions, such as account restrictions or financial adjustments, may require additional authorization and documented reasons.
12. Reporting and Analytics
Analytics can help businesses understand how customers use the application.
Relevant metrics may include registration completion, onboarding abandonment, payment success rates, failed transactions, active users, support volumes, and feature adoption.
Analytics should be designed with privacy in mind.
Sensitive financial details should not be sent to general-purpose analytics tools unless the collection and processing have been properly assessed and authorized.
Advanced Features for a Competitive Wallet Application
After the core product is stable, businesses can consider additional capabilities.
AI-Assisted Fraud Detection
Machine learning models can help identify unusual transaction patterns or suspicious account activity.
Possible signals include transaction frequency, device changes, abnormal usage patterns, and deviations from established behaviour.
AI should support an appropriate risk-management process rather than automatically being treated as proof of fraud.
False positives, model monitoring, explainability, and human review may be important depending on the use case.
Spending Insights
A wallet may categorize transactions and provide summaries of spending activity.
For example, users might see totals for shopping, transportation, dining, and subscriptions.
Such features should clearly explain how transactions are categorized and allow corrections when appropriate.
Loyalty and Rewards
Businesses can combine payments with points, cashback-style rewards, vouchers, or membership benefits.
The rules for earning and redeeming rewards should be transparent, including expiration dates, restrictions, and refund handling.
Multi-Currency Support
A multi-currency wallet may display balances or transactions in several supported currencies.
Businesses must account for exchange-rate sources, conversion timing, fees, rounding, refunds, and currency-specific transaction rules.
Displaying a currency conversion estimate does not guarantee that the final transaction will use the same rate.
Wearable and Contactless Integration
Depending on the platform, provider, and supported hardware, a wallet may integrate with contactless payment infrastructure or wearable devices.
These capabilities can require additional provisioning, device security, platform approvals, and payment-network support.
They should be assessed before they are included in an initial development budget.
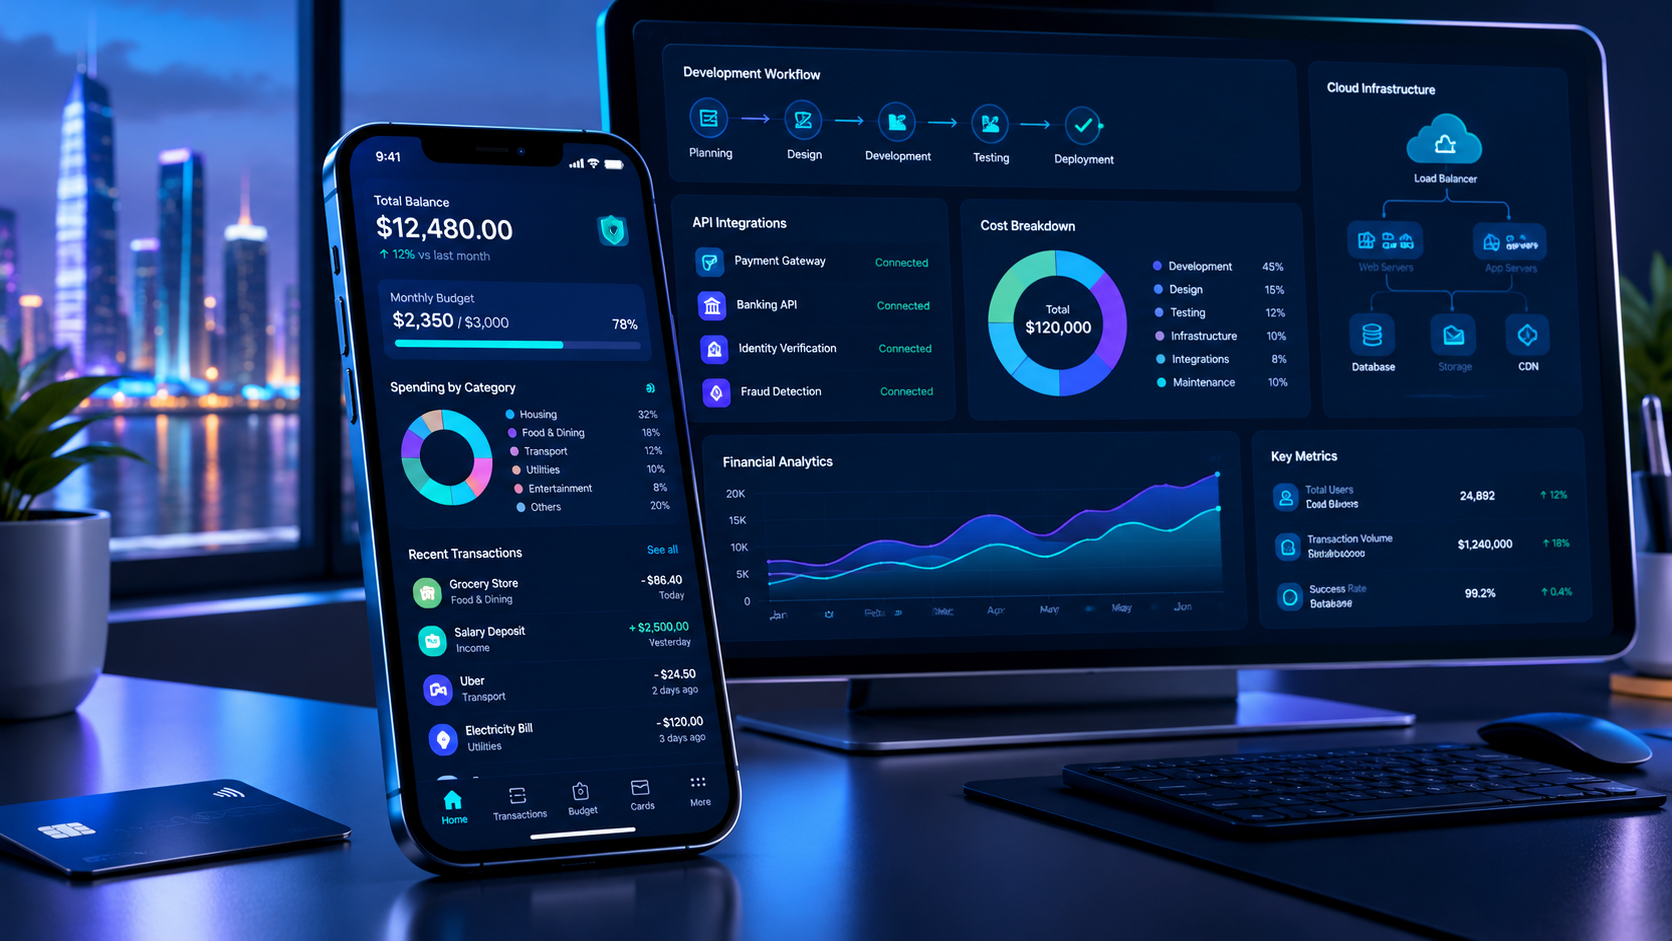
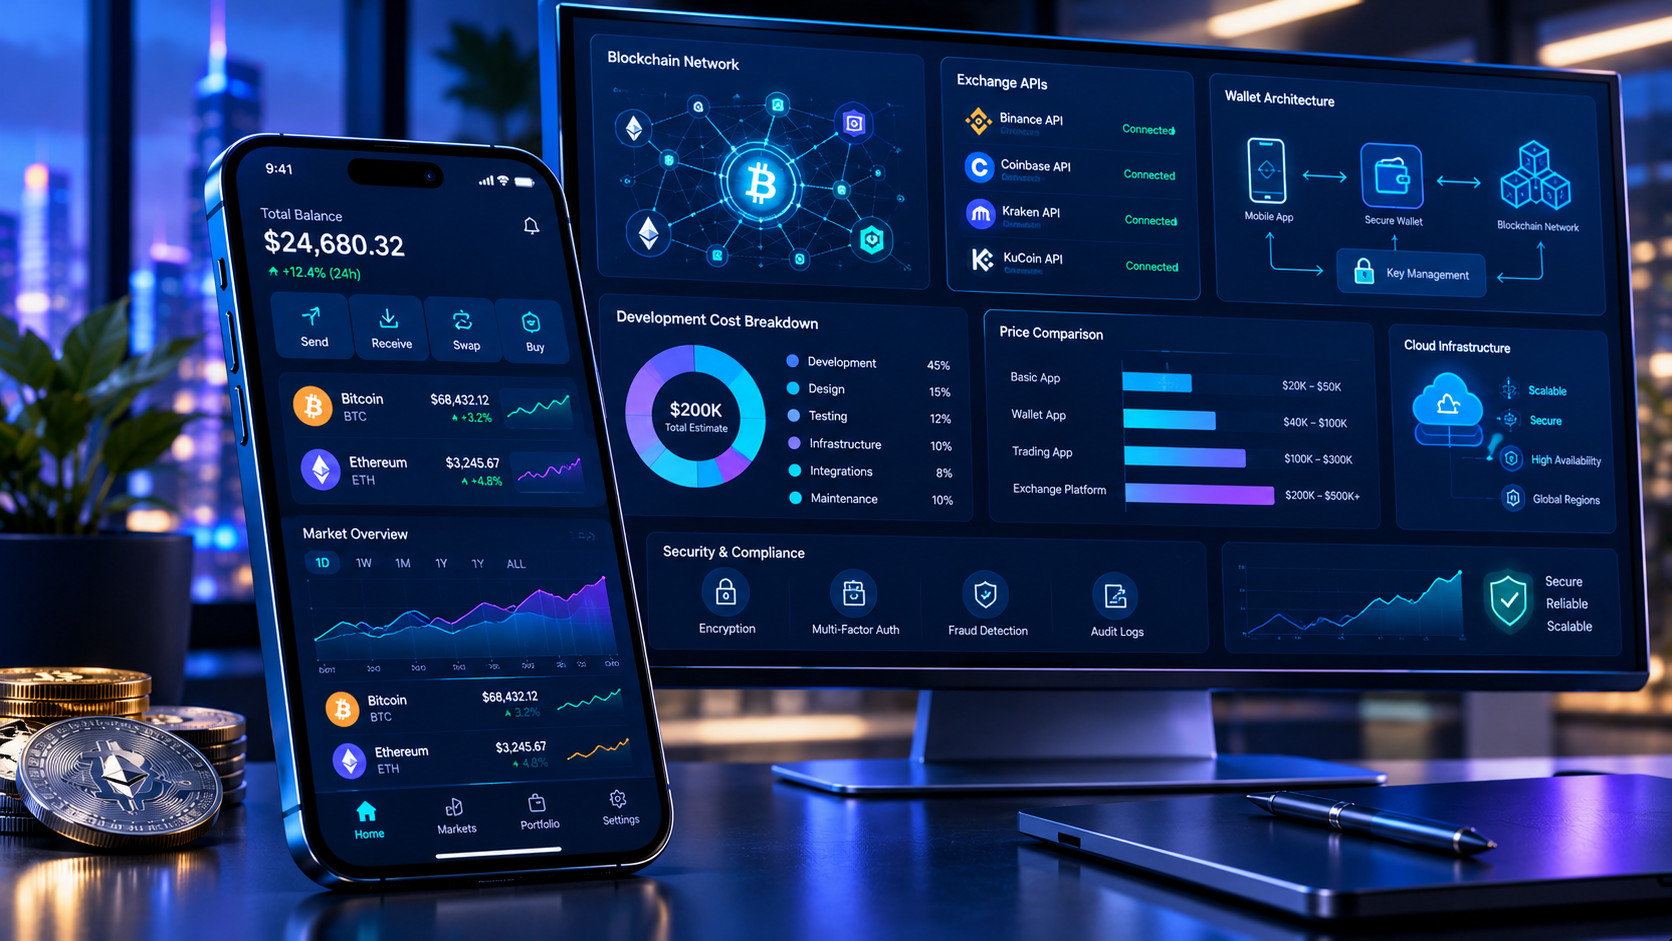
How Much Does Wallet App Development Cost in 2026?
The cost of wallet app development depends on the application type, feature set, number of platforms, backend complexity, financial integrations, security requirements, and regulatory scope.
There is no single price that applies to every digital wallet.
The following figures are illustrative planning estimates, not verified market averages or a development quotation. Actual costs can differ significantly by vendor, location, architecture, and project requirements.
Estimated Wallet App Development Costs
Development level | Typical scope | Illustrative cost in USD | Approximate equivalent in QAR |
|---|---|---|---|
Basic wallet MVP | Registration, basic dashboard, transaction history, and a limited integration | $20,000–$45,000 | QAR 73,000–164,000 |
Mid-level wallet | More complete user accounts, payment integration, notifications, admin dashboard, and transaction workflows | $45,000–$100,000 | QAR 164,000–364,000 |
Advanced digital wallet | More complex transaction processing, multiple integrations, enhanced risk controls, and expanded operational tools | $100,000–$250,000+ | QAR 364,000–910,000+ |
Complex financial platform | Advanced multi-service wallet, extensive integrations, sophisticated controls, and high-availability architecture | $250,000–$500,000+ | QAR 910,000–1,820,000+ |
The QAR figures use an illustrative conversion of approximately QAR 3.64 per US dollar. They are rounded planning equivalents, not quoted prices.
These ranges refer to software project development and can exclude payment-provider charges, legal advice, licensing, independent compliance assessments, specialized audits, and ongoing operations.
A regulated wallet that holds customer funds or operates its own payment services may require substantially more investment than a wallet interface integrated with an established payment provider.
What Affects the Cost of Wallet App Development?
1. Number of Platforms
Developing for iOS, Android, and the web can increase design, implementation, testing, and maintenance requirements.
Cross-platform development can reduce duplicated work, but it does not eliminate platform-specific testing or native integration requirements.
2. Backend Architecture
The backend may manage user accounts, transaction records, payment integrations, notifications, identity verification, reporting, and administrative workflows.
A wallet with complex transaction rules requires more extensive backend engineering than a simple application that displays externally managed payment information.
3. Payment Integrations
Connecting to payment gateways, banks, payment service providers, merchant systems, or transfer infrastructure requires integration work and testing.
The complexity depends on provider documentation, API capabilities, approval processes, transaction types, and the required reconciliation procedures.
4. Security Requirements
Financial applications need appropriate authentication, encryption, secure key handling, authorization controls, monitoring, and security testing.
The cost depends on the risks being addressed and the assurance requirements of the product.
5. Regulatory and Compliance Scope
The project budget may need to account for identity verification, compliance workflows, record retention, transaction monitoring, independent assessments, and specialist legal or regulatory advice.
These expenses should be considered separately from ordinary application development.
6. UI/UX Design
A wallet must make payments, balances, fees, and transaction states understandable.
Clear interfaces are especially important when an incorrect action could result in a financial loss.
Complex onboarding, accessibility requirements, multilingual support, and extensive user testing can increase design costs.
7. Testing and Quality Assurance
Testing should cover normal transactions, failed payments, network interruptions, duplicate requests, concurrent activity, refunds, and reconciliation.
The effort required depends on the number of integrations and the consequences of errors.
8. Ongoing Maintenance
Wallet applications require continued support after launch.
Maintenance can include operating-system compatibility updates, dependency upgrades, bug fixes, security patches, monitoring, infrastructure management, and integration updates.
Example: Budgeting for a Wallet MVP
Suppose a business wants to build an iOS and Android wallet that integrates with an established payment provider.
The initial scope includes:
User registration and secure login.
A wallet dashboard.
Payment initiation through the provider.
Transaction history.
Push notifications.
A basic administrative dashboard.
Testing and deployment preparation.
The business could begin with a discovery phase to establish the payment provider's capabilities, required onboarding process, transaction flows, and security responsibilities.
The development team could then prepare a detailed quotation based on confirmed requirements.
This approach is more reliable than estimating the budget from the number of screens alone.
How Long Does It Take to Develop a Wallet App?
Development time depends on complexity, integration availability, approval requirements, and the amount of functionality included in the initial release.
The following timelines are illustrative estimates for planning, not guaranteed delivery dates.
Project type | Indicative development timeline |
|---|---|
Basic wallet MVP | 8–14 weeks |
Mid-level wallet | 3–6 months |
Advanced digital wallet | 6–10 months |
Complex financial platform | 9–15 months or longer |
These estimates assume that requirements and dependencies can be established in a timely manner. Third-party approvals, regulatory processes, and provider onboarding may extend the overall launch schedule.
Wallet App Development Timeline by Stage
Stage 1: Discovery and planning — 1–3 weeks
Define the target audience, business model, payment flows, regulatory dependencies, initial features, and success metrics.
Stage 2: UI/UX design — 2–4 weeks
Create user journeys, wireframes, interface designs, and interactive prototypes.
Stage 3: Architecture and backend development — 3–8 weeks
Design the database, transaction model, API structure, authentication system, and administrative workflows.
Stage 4: Mobile app development — 4–10 weeks
Build the user interface, connect APIs, implement required features, and handle platform-specific functionality.
Stage 5: Integrations and testing — 3–8 weeks
Test payment flows, error handling, security controls, transaction reconciliation, and device compatibility.
Stage 6: Deployment preparation — 1–3 weeks
Prepare release builds, operational documentation, support processes, monitoring, and store submissions where applicable.
These stages may overlap. Their durations should not simply be added together to produce a guaranteed project schedule.
Payment-provider onboarding and regulatory approvals may run alongside development, but their completion dates are not entirely controlled by the software team.
Best Technologies for Wallet App Development
The right technology stack depends on the required platforms, transaction architecture, integration environment, team expertise, and long-term maintenance strategy.
1. Mobile App Development Technologies
Flutter
Flutter allows teams to build applications for multiple platforms using a shared codebase.
It can be suitable for wallets that need a consistent user interface across iOS and Android.
Native integrations may still be needed for specific device capabilities, payment SDKs, and security features.
React Native
React Native enables cross-platform application development using JavaScript or TypeScript and React.
It can be appropriate for teams with existing React expertise or projects that benefit from shared application logic.
Platform-specific components may still be required for some payment and device integrations.
Native iOS Development
Swift and Apple's native development tools can be appropriate when the wallet depends heavily on iOS-specific functionality or requires extensive native integration.
Native Android Development
Kotlin and Android development tools can be appropriate for applications that require detailed control over Android-specific behaviour and integrations.
There is no universally best choice. The correct approach depends on the product's requirements and the available engineering expertise.
2. Backend Technologies
The backend coordinates application requests, user accounts, transaction workflows, payment-provider integrations, and operational processes.
Possible technologies include:
Node.js with TypeScript.
Java with Spring Boot.
C# with ASP.NET Core.
Python with suitable backend frameworks.
PHP with Laravel.
The choice should consider maintainability, performance, security, team experience, and integration requirements.
For financial transaction processing, architecture and correctness are more important than selecting a language solely because it is popular.
3. Database Technologies
A wallet may use a relational database such as PostgreSQL or MySQL for transactional records and account-related data.
Additional technologies may support caching, queues, analytics, and reporting.
The system should define how balances, transaction entries, reversals, and reconciliation records remain consistent.
For systems handling money, an auditable ledger design and appropriate transaction boundaries are essential.
4. Cloud Infrastructure
Cloud infrastructure can support application hosting, databases, monitoring, backups, and scaling.
The selection of a cloud provider should consider:
Availability and disaster recovery.
Data protection requirements.
Access management.
Encryption and key management.
Monitoring and incident response.
Data residency and contractual obligations.
Expected traffic and operating costs.
Businesses can explore cloud and DevOps solutions when planning the infrastructure and operational processes behind a wallet application.
5. APIs and Integration Architecture
APIs connect the mobile application to backend services and external providers.
A wallet may require APIs for identity verification, payment initiation, transaction status, notifications, merchant systems, and reporting.
Integrations should include authentication, authorization, input validation, timeouts, retry handling, rate limiting, and appropriate logging.
Sensitive credentials should never be embedded as permanent secrets in a mobile application.
Security Requirements for a Digital Wallet
Security must be built into the application from the planning stage rather than added after development.
Wallets handle sensitive information and may facilitate financial transactions, making security failures particularly consequential.
1. Encryption and Secure Key Management
Sensitive data should be protected in transit and, where appropriate, at rest.
Cryptographic keys should be managed using suitable key-management facilities rather than being hard-coded into the application.
Sensitive authentication material should not be stored in ordinary application preferences or exposed through logs.
2. Strong Authentication
Authentication controls should match the risk of the application and the requested action.
Options include multi-factor authentication, biometric authentication through supported operating-system facilities, secure session management, and step-up verification for higher-risk transactions.
Biometric verification on a device should not be treated as a replacement for every backend authorization control.
3. Transaction Authorization
Every financial transaction should be authorized and validated by the trusted backend or relevant payment infrastructure.
The system should verify the user, payment amount, destination, available funds where applicable, transaction limits, and relevant risk controls.
A modified mobile interface must not be able to authorize a payment simply by changing a displayed value.
4. Fraud Prevention
Appropriate controls may include:
Transaction limits.
Rate limiting.
Device and session risk signals.
Unusual activity detection.
Suspicious login monitoring.
Velocity checks.
Account recovery safeguards.
Investigation and escalation procedures.
The exact controls should be based on the service's risks and applicable requirements.
5. Secure API Design
Wallet APIs should validate requests and enforce authorization for every sensitive operation.
Security measures can include short-lived access tokens, secure refresh-token handling, request validation, replay protection where appropriate, and controlled administrative permissions.
Developers should test whether users can access other users' transaction records by manipulating identifiers or requests.
6. Payment Card Security
Where payment cards are involved, businesses should assess applicable payment-card security obligations and the scope of their payment architecture.
Using a payment provider and tokenization can reduce the need to handle raw card data directly.
It does not automatically eliminate all compliance responsibilities.
7. Security Testing
Before launch, testing should cover authentication, authorization, API security, data exposure, session handling, transaction manipulation, and relevant mobile application risks.
Independent penetration testing may be appropriate depending on the risk and assurance requirements.
Security should continue after launch through monitoring, patching, incident response, and periodic reviews.
Businesses can also review Galaxium Coding's mobile application development services when planning secure mobile software and its supporting architecture.
Wallet App Development in Qatar: What Businesses Need to Know
Qatar is an important market to consider when designing a wallet for local customers, merchants, or financial-service users.
However, a product intended for Qatar should be designed around its actual payment model rather than assuming that every wallet requires the same integrations or permissions.
1. Understand Qatar's Payment Infrastructure
The Qatar Central Bank's Qatar Mobile Payment information describes a national mobile payment system connecting participating banks and authorized payment service providers.
The system supports eligible wallet-to-wallet transfers and QR-code merchant payments. Its published information also describes registration requirements for users.
This infrastructure is relevant when assessing whether a proposed wallet could use an existing participating provider rather than building an independent payment network.
Businesses should confirm current provider participation, available APIs, onboarding requirements, and technical integration options directly with the relevant provider.
2. Review Licensing and Regulatory Requirements
A business developing a wallet must distinguish between creating software and providing a regulated financial service.
The Qatar Central Bank's Payment Services Regulation addresses payment services and includes definitions relevant to e-money and electronic wallets.
Depending on the product, activities involving stored value, money transfers, payment processing, or other financial services may trigger regulatory obligations.
Before implementation, businesses should obtain qualified advice on the applicable requirements and confirm whether the intended operating model requires authorization.
Developing a wallet application does not, by itself, authorize a company to provide regulated payment services.
3. Support Qatari Riyals
For wallets targeting Qatar, QAR should be supported where appropriate for the intended service.
The application should handle currency display, transaction amounts, rounding, receipts, refunds, and reporting consistently.
If multiple currencies are supported, conversion rates, fees, settlement currencies, and the timing of conversions should be explained clearly.
4. Plan Identity Verification
Customer onboarding should reflect the requirements of the chosen provider and applicable regulations.
For example, the QMP system's published information identifies QID requirements for citizens and residents, and passport and entry-visa documentation for visitors.
These are system-specific requirements and should not automatically be assumed to apply identically to every wallet or financial service.
The selected provider should confirm the actual onboarding process for the proposed product.
5. Integrate With Local Merchants
Merchant-focused wallets may need QR-code payments, merchant onboarding, transaction reporting, refund handling, and settlement information.
Businesses should verify which payment methods and integration options are available from their chosen payment provider.
6. Plan Language and Accessibility
Depending on the intended audience, Arabic and English interfaces may be valuable.
Localization involves more than translating labels. Layout direction, currency formatting, transaction descriptions, customer support, and accessibility should also be considered.
7. Consider Data Protection and Hosting
Businesses should identify the personal and financial information they collect, where it is processed, which providers receive it, and how long it is retained.
Hosting and data-storage decisions should be assessed against applicable legal requirements, contractual obligations, security risks, and operational needs.
A cloud deployment should not be assumed to satisfy every regulatory or data-residency requirement automatically.
How to Develop a Wallet App Step by Step
A structured development process helps businesses reduce uncertainty, identify dependencies, and avoid costly changes.
Step 1: Define the Business Model
Start by deciding what the wallet will do.
Will it manage loyalty points, facilitate payments through a third-party provider, support merchant transactions, or hold monetary value?
Clarify the target users, revenue model, geographic scope, transaction types, and responsibilities of each participating organization.
Step 2: Confirm the Regulatory and Provider Requirements
Determine which activities require authorization, which services will be provided by licensed partners, and what onboarding or transaction restrictions apply.
Identify dependencies before finalizing the technical architecture.
Step 3: Prepare the MVP Scope
Choose the smallest set of features that can deliver a useful, safe, and testable product.
For a wallet using an external payment provider, the MVP might include:
Secure account registration.
User authentication.
Payment initiation through the provider.
Transaction status and history.
Notifications.
Basic administrative tools.
Customer support.
A wallet holding monetary value may require additional capabilities before it can operate appropriately.
Step 4: Design the User Experience
Map the user journey from registration to the first successful transaction.
Design clear screens for payment confirmation, fees, transaction status, failed payments, refunds, and support.
Prototype important flows and test them with representative users before investing in the full implementation.
Step 5: Design the Backend and Ledger
Plan the database, APIs, transaction states, security boundaries, and reconciliation process.
If the wallet manages funds, define an appropriate financial ledger and controls for maintaining accurate records.
A financial ledger should preserve a traceable history of entries and reversals instead of allowing unexplained changes to historical transactions.
Step 6: Develop the Application and Integrations
Build the mobile application, backend services, administrative dashboard, and connections to approved third-party providers.
Use development and test environments where available.
Keep sensitive credentials and privileged operations on appropriately secured server-side systems.
Step 7: Test the Complete Transaction Lifecycle
Testing should cover successful and unsuccessful transactions, duplicate requests, timeouts, refunds, reversed payments, interrupted connections, and delayed provider responses.
Verify that the displayed transaction status matches the authoritative status reported by the relevant system.
Reconciliation tests are especially important when multiple providers or accounts are involved.
Step 8: Prepare for Launch
Before release, complete the necessary provider approvals, security reviews, operational documentation, monitoring, backup arrangements, and customer support procedures.
Prepare store listings and comply with the relevant distribution platform requirements.
A successful technical build is only one part of a successful launch.
Step 9: Monitor and Improve
After launch, monitor availability, transaction success rates, errors, customer complaints, and security alerts.
Use real operational data to prioritize improvements.
Changes to payment integrations and security controls should follow a controlled release process with appropriate testing.
How Can a Wallet App Generate Revenue?
A wallet's revenue model should fit its users, operating costs, and regulatory obligations.
Potential models include the following.
Transaction Fees
A business may receive revenue from eligible transactions where its business model and applicable rules permit charging fees.
Fees should be transparent, and any required disclosures or approvals should be completed.
Merchant Services
A wallet provider may offer services to merchants, such as transaction reporting, payment acceptance integrations, or operational tools.
Revenue may come from service agreements or other permitted commercial arrangements.
Subscription Plans
Some business wallets offer paid plans for advanced reporting, team management, integrations, or additional operational features.
This model is more suitable when the wallet provides continuing business value beyond basic payment functionality.
Loyalty Partnerships
Retailers may fund rewards or promotional campaigns that encourage repeat purchases.
The commercial model should clearly define who funds rewards, when they expire, and how refunds affect them.
Value-Added Services
Depending on the product and applicable permissions, a wallet may support additional services such as expense reporting, business payment management, or financial insights.
The business should avoid assuming that adding a financial feature is legally or technically straightforward simply because it appears in another wallet.
Common Wallet App Development Mistakes
1. Building Before Confirming the Payment Model
Starting development before confirming how payments will be processed can create expensive architectural changes.
Better approach: Identify the payment provider, supported transaction types, integration requirements, and regulatory responsibilities before finalizing the scope.
2. Treating Security as a Final Testing Stage
Security cannot be solved through a single penetration test immediately before launch.
Better approach: Include threat modelling, secure design, authorization checks, and security testing throughout the development lifecycle.
3. Ignoring Transaction Reconciliation
An application may display a payment as successful even when its internal records and the provider's records do not agree.
Better approach: Define authoritative transaction states, reconciliation procedures, exception handling, and auditable correction workflows.
4. Adding Too Many Features to the MVP
Launching with multi-currency transfers, loyalty programmes, AI, complex merchant tools, and multiple external integrations can make the first release expensive and difficult to validate.
Better approach: Prioritize the core use case, validate it, and add further features based on actual demand.
5. Underestimating Third-Party Dependencies
Payment providers, identity verification services, and financial institutions may have their own technical and operational requirements.
Better approach: Confirm documentation access, testing environments, approval procedures, fees, and support arrangements early.
6. Neglecting Maintenance
A wallet can become unreliable if dependencies, APIs, operating systems, and security controls are not maintained.
Better approach: Budget for ongoing updates, monitoring, incident response, and provider integration changes.
How to Choose a Wallet App Development Company
Choosing a development partner requires evaluating both engineering capabilities and its understanding of financial application risks.
Consider these factors before selecting a provider.
Technical Experience
Ask how the team approaches mobile development, backend architecture, API integration, databases, cloud infrastructure, and testing.
Look for relevant, verifiable experience rather than relying only on broad claims.
Financial Integration Knowledge
Ask how the team handles transaction states, idempotency, reconciliation, refunds, provider timeouts, and secure payment integration.
These topics are more revealing than a demonstration of the visual interface alone.
Security Practices
Discuss authentication, access control, encryption, secrets management, security testing, monitoring, and incident response.
Clarify which security activities are included in the proposed scope and which require independent specialists.
Project Transparency
A clear proposal should identify deliverables, milestones, assumptions, exclusions, dependencies, and acceptance criteria.
Payment-provider approval and regulatory work should be explicitly addressed rather than silently included in an unrealistic delivery promise.
Post-Launch Support
Ask how bugs, urgent incidents, security patches, and provider changes will be handled.
Clarify the support period, service expectations, maintenance charges, and responsibility for infrastructure.
Businesses can review Galaxium Coding's projects and portfolio to explore its published work, and read the guide to choosing a mobile application developer for additional guidance.
Future Trends in Wallet App Development
Several developments may influence how wallet products evolve over the coming years.
Embedded Payments
Wallet functionality may become part of shopping, booking, transport, and other everyday applications.
This can reduce friction for customers while increasing the importance of reliable integrations and transparent payment flows.
Programmable Payment Workflows
Businesses may use more automated payment processes for subscriptions, invoices, merchant settlements, and other defined business activities.
These workflows require clear authorization, auditability, and appropriate controls.
AI-Assisted Risk Management
AI-based tools may help identify unusual activity and prioritize suspicious transactions for investigation.
Their effectiveness depends on data quality, monitoring, appropriate controls, and careful handling of false positives.
Greater Emphasis on Interoperability
Users and businesses benefit when payment systems can interact through supported, secure interfaces.
The extent of interoperability depends on participating providers, technical standards, commercial arrangements, and applicable rules.
Stronger Privacy and Security Expectations
Wallet providers will continue to face the need to protect sensitive information, control access, and respond to emerging threats.
Privacy and security should remain ongoing operational responsibilities rather than one-time development milestones.
These trends are planning considerations, not guarantees that every wallet needs every emerging feature.
Frequently Asked Questions About Wallet App Development
1. How much does it cost to develop a wallet app in 2026?
An illustrative budget for a basic wallet MVP might be $20,000–$45,000, while more advanced applications can cost $100,000–$250,000 or more. Complex financial platforms may require budgets exceeding $250,000. Actual costs depend on features, payment integrations, security, regulatory requirements, and the development team.
2. How long does it take to build a digital wallet?
A basic MVP may take approximately 8–14 weeks, while a mid-level wallet may require 3–6 months. Advanced financial applications can take 6–10 months or longer. Third-party approvals and regulatory processes can extend the overall timeline.
3. What features should a wallet app have?
Core features may include secure registration, authentication, a dashboard, transaction history, payment integration, notifications, customer support, and administrative tools. Wallets that manage monetary value may also need balance management, transfers, reconciliation, identity verification, and additional risk controls.
4. Which technology is best for wallet app development?
Flutter and React Native can be suitable for cross-platform applications, while Swift and Kotlin provide native iOS and Android development options. Backend technologies such as Node.js, Java, C#, Python, and PHP can support wallet services. The best stack depends on the application's requirements and the team's expertise.
5. Can a wallet app be developed for Qatar?
Yes. A wallet application can be designed for Qatar, provided the business model, integrations, and operational arrangements comply with applicable requirements. Businesses should assess the Qatar Central Bank's payment infrastructure, the chosen provider's onboarding process, currency requirements, and any licensing obligations relevant to their intended services.
6. Does every wallet app need a financial services licence?
Not necessarily. Requirements depend on the actual activities performed, the product structure, and applicable regulations. A loyalty application or interface that connects to an authorized provider may have a different regulatory profile from a business that issues e-money or independently provides payment services. Obtain qualified advice before launching.
7. Is Flutter suitable for a digital wallet?
Flutter can be suitable for many digital wallets because it supports shared application development across platforms. However, the team must verify compatibility with required payment SDKs, native functionality, device security features, and any platform-specific integration requirements.
8. How can a wallet app be made secure?
Security measures can include strong authentication, encryption, secure key management, server-side transaction authorization, API protection, fraud monitoring, access controls, and regular security testing. The exact controls should be selected based on the wallet's risks and regulatory obligations.
9. Can a wallet app integrate with banks and payment gateways?
Yes, where the relevant institutions and providers offer suitable integration options and approve the arrangement. The implementation may involve APIs, authentication, payment-status updates, reconciliation, error handling, and provider-specific testing.
10. Can a digital wallet support multiple currencies?
Yes, if the product architecture and participating providers support the required currencies. The design should address exchange rates, fees, rounding, refunds, settlement, and applicable financial-service requirements.
11. What is the difference between a digital wallet and a payment gateway?
A digital wallet is an application or service that manages supported payment credentials, monetary value, or payment-related functionality for users. A payment gateway facilitates the transmission and processing of payment information between relevant parties. A wallet may integrate with a payment gateway, but the two are not the same product.
12. What are the ongoing costs of running a wallet app?
Ongoing expenses may include cloud infrastructure, monitoring, software maintenance, security reviews, customer support, payment-provider charges, identity verification, messaging, and compliance-related work. The total depends on transaction volumes, service requirements, and the operating model.
13. Should a business build a custom wallet or use an existing payment provider?
A custom wallet may be appropriate when a business needs a tailored user experience, specialized workflows, or integration with its own services. Using an established payment provider can reduce the need to build and operate parts of the payment infrastructure independently. The right choice depends on the required control, cost, capabilities, regulatory scope, and time to market.
14. Can a wallet app be launched as an MVP?
Yes, provided the MVP is complete and appropriate for its intended use. A wallet that only manages loyalty points may have a simpler initial scope than a regulated product that holds monetary value. Essential security, transaction correctness, and applicable legal requirements should not be deferred merely to launch sooner.
Conclusion: Plan Your Wallet App for Long-Term Success
Wallet app development in 2026 requires a clear business model, thoughtful product design, reliable integrations, and strong security practices.
The most effective approach is to define the wallet's purpose first, establish its financial and regulatory boundaries, and prioritize the features that solve the intended users' problems.
Development costs can range from tens of thousands of dollars for a limited MVP to several hundred thousand dollars or more for a complex financial platform. The actual budget depends on the application's scope, architecture, integrations, security requirements, and operating model.
For businesses in Qatar, payment infrastructure, local provider relationships, QAR support, identity verification, and applicable Qatar Central Bank requirements should be assessed early in the project.
Galaxium Coding supports businesses seeking tailored digital solutions through its mobile application development services and custom software development services.
If you are planning a wallet application, start by defining the required user journeys, payment model, integrations, and MVP features. You can then contact Galaxium Coding to discuss your software requirements and explore an appropriate development approach.